Autor Cointelegraph by

Paper losses and scrapped ETFs. What Trump Media’s 2,650 BTC transfer really means

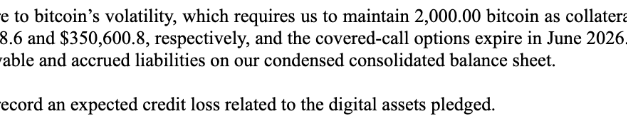
However, this model cuts both ways. On one hand, it lets companies raise capital on a wave of market optimism. On the other, it forces them to absorb the volatility of the underlying asset when prices fall.For a public company, the situation is even more complicated. Accounting obligations mean financial losses quickly become public, and any asset movements against that backdrop attract intense scrutiny.The recent discussion around Trump Media & Technology Group (TMTG) shows exactly that. Amid paper losses on its crypto strategy, the company moved 2,650 BTC to Crypto.com, having previously withdrawn applications to launch its own cryptocurrency ETFs.The market absorbed this news fairly calmly, but the obvious question remains: is this part of a trading strategy, or preparation for a forced sale of digital assets?Behind the $200 million moveTrump Media was not created as a financial or investment entity, but rather as a technology holding company. Its flagship product is Truth Social — a social network launched after Donald Trump was banned from major platforms.In March 2024, the company went public through a SPAC merger. Until the following spring, TMTG remained strictly within the social media sphere, and only then did management decide to pivot, beginning the formation of a cryptocurrency reserve.For these purposes, the company raised approximately $2.3 billion through equity sales and the issuance of zero-coupon convertible secured notes.Initially, the organization stated that it wanted to establish a Bitcoin reserve, with Crypto.com and Anchorage Digital serving as its custodial partners. In practice, the model turned out to be broader than initially declared.The company invested in the Cronos (CRO) token, which is affiliated with the aforementioned Crypto.com, and filed applications to launch several cryptocurrency ETFs at once.However, the cryptocurrency strategy has apparently failed to pay off.As of December 31, 2025, Trump Media disclosed holdings of 9,542 BTC with a cost basis of $1.131 billion and a fair value of $836.4 million, alongside 756 million CRO with a cost basis of $113.9 million and a fair value of $68 million.The company’s first-quarter 2026 report made the financial pressure even more evident. TMTG kept the same BTC and CRO balances on its books, but their fair value dropped to $647 million and $53 million, respectively.Separately, TMTG disclosed an unrealized loss on digital assets of nearly $244 million (including pledged assets). Meanwhile, the company’s net loss is estimated at $405.9 million.A few days after the report’s publication, the company also withdrew its applications to launch ETFs. Then, in late May, addresses linked by Arkham to Trump Media transferred 2,650 BTC to Crypto.com infrastructure — amounting to over $200 million at the market prices at the time of writing.Some interpret such transactions as preparation for a sale or, at the very least, securing liquidity for over-the-counter (OTC) deals. However, the U.S. Securities and Exchange Commission (SEC) does not require companies to disclose public wallet addresses, which makes it difficult for outsiders to independently verify their intentions.Companies often use such transfers to post collateral for fiat-denominated loans. In particular, TMTG said in its quarterly report that it had pledged 4,260 BTC as collateral for its convertible notes.Another 2,000 BTC was transferred to a third-party partner as insurance for options trading. That partner also received the right to move those assets freely at its own discretion.Excerpt from Form 10-Q. Source: SEC.A TMTG representative also said the Bitcoin had been “transferred, but not sold,” describing the move as part of a broader trading strategy.The market reacted fairly calmly to both the loss data and the transfer of Bitcoin to the exchange. That is likely because such an adverse scenario had already been priced in.Since the beginning of 2026, the stock price of Trump Media & Technology Group (DJT) has fallen by nearly 40%. Source:  TradingView.From the outset, many analysts expressed skepticism over Trump Media’s ability to secure a foothold in an overheated crypto ETF market dominated by giants like BlackRock and Fidelity. The situation was further compounded by the fact that TMTG’s proposed products featured virtually no structural differences from those of its competitors, relying instead primarily on marketing and the political brand.The illusion of onchain transparencyThe Trump Media case exposes a systemic issue: despite the transparency of the blockchain, tracking the actual state of corporate crypto reserves remains exceptionally difficult. A large onchain transfer can represent either a forced liquidation or a routine operational process with no underlying intention to divest the assets.However, public company status dictates its own rules. To prevent panic among traditional investors, management is forced to explain nearly every movement of funds. Under these conditions, clear and timely communication becomes just as vital as the financial strategy itself.Furthermore, such precedents bring a major regulatory dilemma to the surface. Should the SEC require public companies to disclose their blockchain addresses to enable a full independent audit? Or are wallets a trade secret, the disclosure of which would make executing corporate trading strategies impossible? This question remains unanswered for now.As for TMTG specifically, the company’s crypto business does not yet look like a sustainable operation with clear economics. The deal with Crypto.com’s parent structure and the sudden withdrawal of ETF applications increasingly resemble an ad hoc search for a model to monetize a political brand, rather than a calculated, long-term strategy.Ultimately, the main intrigue is not whether the company will sell its Bitcoin. The question is broader. Can such a structure, in principle, withstand the pressure of an aggressive crypto strategy over the long haul?

Čítaj viac
The Nobitex dilemma: How Iran's biggest crypto exchange stays off the OFAC blacklist

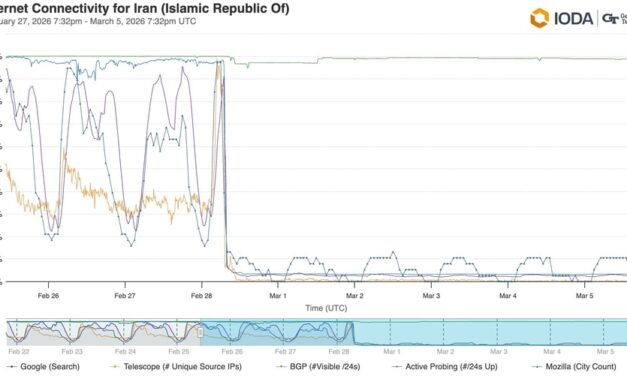
Iran’s internet formally remained part of global routing, but user activity fell almost to zero. That points to a managed restriction on citizens’ access to the external network. Source: IODA.But in that digital darkness, one vital financial service continued to operate without interruption: Nobitex, a cryptocurrency exchange linked to Iran’s ruling elite.We compiled the available information about the platform and tried to understand how Iranian authorities use it, what investigations by analytics firms have revealed, and why, despite all these findings, the exchange is still not on OFAC’s SDN List.The scale and scope of Iran’s crypto giantNobitex is far from a niche platform. While estimates vary, analysts agree that the asset flows moving through the exchange are measured in the billions of dollars. For instance, TRM Labs recorded an observed volume of approximately $5 billion between 2025 and March 2026.Earlier, Chainalysis noted that asset inflows to Nobitex addresses exceeded the combined figure for Iran’s 10 other largest exchanges. Source: Chainalysis.Nobitex has an extensive retail user base. According to the platform’s own figures, it serves about 11 million Iranians — almost 12% of the country’s population.The exchange offers a suite of services typical for the industry: spot and margin trading, yield-bearing products, liquidity pools, digital gift cards, and even crypto-collateralized lending. Nobitex also caters to professional market participants and institutional players. These entities are provided with specialized terms, such as increased limits and high-speed APIs.What drew attention to the platform, however, wasn’t its retail operations. It was information suggesting Nobitex functions as a national currency gateway for a country cut off from SWIFT.Shadow banking networkA series of investigations available online focus on how Nobitex helps the Iranian leadership evade economic sanctions. In January 2026, Elliptic published a report detailing systematic purchases of the USDT stablecoin by Iran’s central bank. According to the company, transactions totaling at least $507 million were carried out through a broker in the UAE, with the assets sent “primarily” to Nobitex. Since the stablecoins could be sold for rials, the regulator was effectively carrying out a foreign exchange intervention outside the international banking system.This is far from the only use case for the exchange by the state. A recent Reuters investigation linked the platform’s founders — brothers Ali and Mohammad Kharrazi — to one of the country’s most influential political and clerical families. The agency also established that one of the largest early investors in the exchange was Mohammad Baqer Nahvi, vice president of Safiran Airport Services — a company placed on the OFAC SDN List in September 2022 for organizing flights to supply Iranian drones to Russia. Separately, Elliptic and Chainalysis have documented Nobitex’s links to wallets associated with Hamas, the Houthi Ansar Allah movement, the propaganda outlet Gaza Now and the sanctioned Russian exchange Garantex.The exchange itself appears to have built its infrastructure from the outset for operating under sanctions.In June 2025, the platform’s source code and portions of its internal documentation were leaked online. According to this data, the code contained modules for generating stealth addresses, transaction batching and splitting, endpoint switching, and specific logic designed to bypass compliance checks. A document titled “Nobitex Privacy” was also made public, explicitly describing a strategy to evade FinCEN tools and Western blockchain analytics. Half measures or strategic restraint?In April 2026, reports surfaced that Iranian entities were charging vessel operators fees in cryptocurrency for unobstructed passage through the Strait of Hormuz. Cryptocurrency has reportedly become one of the primary payment options for these transactions. The practice appears to have been quite successful, suggesting that digital assets will continue to be used for similar purposes.Against this backdrop, adding Nobitex to the SDN List by analogy with Garantex may seem like a logical step, even though such flows usually don’t pass through retail platforms. Yet that hasn’t happened.The U.S. Treasury Department has previously sanctioned Iran-linked cryptocurrency exchanges, but those platforms were registered in the United Kingdom. Nobitex, by contrast, is incorporated in Iran as a purely local company.Crucially, on the same day Reuters published its investigation into Nobitex, OFAC clarified that Iranian digital asset exchanges are already considered blocked financial institutions, regardless of whether they are individually named on the SDN List.For a platform physically based in Iran, however, this has little practical effect: its core operations revolve around Iranian users and neutral foreign intermediaries.An SDN listing functions differently. It triggers secondary sanctions against any non-U.S. counterparties worldwide, provides direct justification for bulk asset freezes by stablecoin issuers, and compels foreign exchanges and OTC desks to sever ties or risk being designated themselves.Why an individual SDN listing may be redundantThe U.S. Treasury has not explained why an individual SDN listing for Nobitex has not followed. However, it is worth noting that the department has never added platforms incorporated within Iran to the list — and there are several of them. OFAC’s strategy toward Iran’s local crypto market is built around targeted measures. Three main approaches stand out:Sanctions against specific addresses.Designation of exchange houses — a recent example being the addition of exchanges allegedly servicing the state’s shadow oil revenues.Designation of individuals and OTC brokers.When it comes to Nobitex itself, any explanation can only be speculative. The first has already been outlined: OFAC employs a different strategy toward local Iranian platforms, and Nobitex simply falls within that logic rather than outside it.The U.S. Treasury may also consider such measures redundant. As previously noted, U.S. persons are already prohibited from transacting with Iranian exchanges; from the standpoint of formal access, an individual listing adds little to existing restrictions.There is also the “human shield” hypothesis. Speaking to Reuters, Nick Smart, Chief Intelligence Officer at Crystal Intelligence, noted that the platform hosts a high concentration of activity from ordinary Iranians. He suggested that separating the regime from the citizens using the exchange is nearly impossible, as their assets are commingled.In this context, the Garantex case looks like the opposite scenario: the platform operated as a B2B hub for shadow capital. That made it possible to physically seize its servers without causing social damage to retail users.There is no direct public confirmation that this is the logic holding OFAC back.Finally, a strike against Nobitex may be viewed as less effective without a simultaneous move against external “exits.” The value of sanctions arises not at the “entry point,” but where funds leave the country: foreign exchanges, stablecoin issuers, OTC brokers, banks, and other intermediaries.The double-edged swordThe Nobitex case is another reminder that the mass adoption the industry dreams of is a double-edged sword.On one hand, the exchange gives Iranians cut off from the world a measure of financial freedom: a way to shield savings from rial inflation and retain at least some access to dollar liquidity. On the other, the state uses the same infrastructure for its own purposes, ranging from central bank currency interventions to transfers to regional proxies.The key point is that this is no longer an isolated practice. Chainalysis places Iran alongside Russia and North Korea, noting that for all three states, “what were once experimental and opportunistic tactics have matured into institutionalized strategies embedded within national economic and security policy.”The Iranian model — a mass retail platform based in an unreachable territory coupled with offshore proxy structures — looks like a working template. Future sanctioned regimes will likely look to this experience.That raises a reverse question — this time for regulators themselves. What is the acceptable cost of sanctions pressure when the regime’s funds and the savings of millions of ordinary users are physically commingled on a single platform? Can the assets of 11 million people be frozen to cut off the state’s financial channel — or is that precisely the line the SDN mechanism, in its current form, does not cross?OFAC has yet to provide a public answer, and the Nobitex case only sharpens the debate.

Čítaj viac

Získaj BONUS 8 € v Bitcoinoch

nakup bitcoin z karty

Registrácia Binance

Burza Binance

Aktuálne kurzy