Autor Cointelegraph by Christina Comben

Winners and losers of the SEC’s new tokenized stocks rules

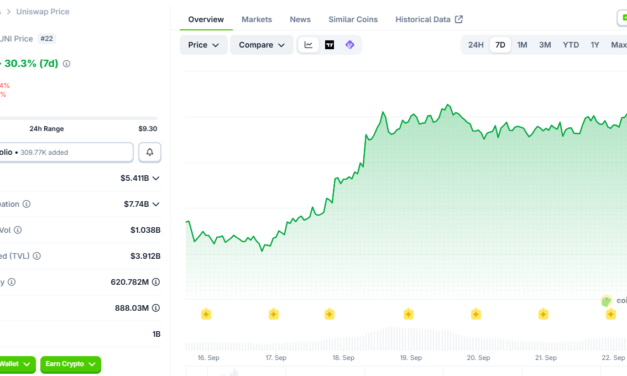
“Tokenization is coming to America,” said Robinhood chief executive Vlad Tenev after the SEC announced its Innovation Exemption last week — and it seems the markets looked kindly on the development.BTC and ETH soared over 10%, and Uniswap’s UNI token — a protocol that looks as it if could become prime real estate for tokenized stock trading — gained more than 30% in the days that followed.While the Securities and Exchange Commission has indeed greenlit tokenized stocks in America, most of the existing stock tokens fall outside of the new rules. The commission’s new five-year Innovation Exemption creates a path for certain venues to trade tokenized National Market System (NMS) stocks onchain without registering as a securities exchange, and for third parties to tokenize stocks — but only under a specific set of conditions. Tokens must give holders the same “rights and privileges” as the underlying shares and trading venues need to permission users and pools.Related: Kraken brings DeFi yield to tokenized stocks and ETFsNot all tokenized stocks are created equal. A token can look like a share and track the price of a share without providing the shareholder rights of a share. Under the new rules that’s classified as a synthetic stock and it’s not compliant.UNI gained over 30% after the SEC announcement. Source: CoingeckoThat means some of the industry’s biggest players may already have a head start, while others will have to play catch-up. As Ondo Finance’s head of global regulatory affairs, Peter Curley, tells Magazine: “Not everything we do will fit, and that’s fine. What matters is that the SEC acted instead of waiting on Congress to finish the job.” The SEC’s tokenization lane is narrowThe SEC’s Sept. 17 order gives certain venues temporary relief from having to register as exchanges when they trade tokenized NMS stocks through permissioned AMM liquidity pools.In other words, the agency has opened a lane for onchain stock trading, but it’s a fairly specific one, and the token itself becomes just as important as the venue.To qualify, a tokenized stock must give holders the same dividends and voting rights as the underlying security. While a third party can tokenize a stock without being affiliated with the issuer, the issuer gets a chance to nix the token before it can be traded.That rules out synthetic exposure which is bad news for Robinhood’s Stock Tokens and Kraken’s xStocks in their current forms. Commissioner Hester Peirce stressed that the exemption covers one particular model rather than every possible way of trading tokenized securities, although she said the SEC is open to other models outside the TSV structure.The products closest to the SEC’s modelCoinbase’s stock tokens are in the ballpark. On Sept. 14, chief executive Brian Armstrong said the company had “set the standard” with its tokenized stocks, as they are not synthetic or debt instruments, but are “real fully-backed securities, redeemable for the underlying shares, with dividends integrated,” and voting rights “coming soon.”Related: Robinhood chain to generate $160M in annual fees by 2028: BernsteinHowever, Coinbase’s current tokenized stock offering is for non-US customers, and its exchange infrastructure is built around a central limit order book. The SEC’s exemption is built around TSVs providing permissioned AMM liquidity pools. Coinbase operates the Base network however, so it has options in that regard.Ondo launched tokenized US securities in June, with the underlying shares held in traditional custody and the token representing the investor’s entitlement onchain. SEC issues Innovation Exemption. Source: SECIt also acquired Oasis Pro, which includes an SEC-registered broker-dealer, ATS and transfer agent, with infrastructure across the traditional and onchain sides of the market.Curley says the SEC’s exemption favors “exactly the model we’ve already proven out: custodial, entitlement-based, with real shareholder rights and corporate actions passing through to the holder.” However, he adds, “we’re not assuming anything clears automatically.”Both Coinbase and Ondo have pieces of the infrastructure the SEC seems to want. Neither can assume its existing setup qualifies without some finessing, but they may have less to rebuild. Uniswap’s permissioned pools could open the doorThe SEC exemption is specifically designed around permissioned AMM liquidity pools, which looks like being good news for Uniswap.The protocol introduced Permissioned Pools for v4 in July, allowing regulated assets to trade through AMMs with compliance enforced directly onchain. While that doesn’t make Uniswap itself a TSV, its v4 infrastructure could be used by operators building one, as Permissioned Pools let issuers control who can trade or provide liquidity, which is consistent with the SEC’s requirements.Permissioned access requires Know Your Customer (KYC) verification, record keeping, public notices and transaction transparency. If that infrastructure can be connected to the shareholder rights and regulatory infrastructure required for US securities trading, Uniswap potentially has a framework that could be adapted to the SEC’s model. Robinhood has the users, but not the right product Robinhood already has around 200 stock tokens trading on Robinhood Chain, which Tenev has described as one-to-one backed and fully DeFi composable.But the head of research at Four Pillars, Jaewon Kim, pointed out that the SEC’s order excludes synthetic exposure, which rules out products like Stock Tokens and Kraken’s xStocks.Robinhood’s Stock Tokens are tokenized debt securities issued by Robinhood Assets (Jersey) Limited. That means they provide economic exposure to the underlying stocks but don’t give holders legal or beneficial rights. They’re also not registered under US securities laws and not available to US persons.Chairman Paul Atkins says the period will allow the market to “develop.” Source: SEC But while Robinhood’s existing product doesn’t fit the SEC’s rules, its distribution and blockchain infrastructure could give it a big advantage if it can adapt its model to the new requirements. Kraken’s xStocks are fully backed by underlying equities but they also don’t give holders the same rights as conventional shares. And being backed by shares is not enough to qualify for this exemption. Bryan Choe, head of research and operations at RWA.xyz, a market intelligence platform for tokenized real-world assets (RWAs), says most existing tokenized equity products are currently third-party sponsored, but he expects that to change in the next 12 months. He tells Magazine, “We expect most of the products to shift to issuer-sponsored models.” He says the exemption “aligns the token issuers with the stock issuers,” and could bring more balance between different issuance models.Five years to prove tokenized stocks are actually betterThe SEC describes the exemption as temporary, and chairman Paul Atkins says the five-year-long period will allow the market to “develop” while the commission “evaluates future rulemaking.”Beyond which company gets the first compliant venue, the real test is whether tokenized stocks will take off in the first place. As Curley says, investors need to end up with something “faster, cheaper, or more useful than a conventional brokerage position.” Questions have already been raised over whether the fragmented liquidity for stock tokens will provide good prices or a decent user experience.The exemption could enable 24/7 trading, fractional ownership, faster settlement, onchain composability and shareholder rights. But at the end of the day, those advantages only matter if investors actually care.Related: Is there any chance left to save the CLARITY Act?Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Čítaj viac
Big Questions: Does Satoshi actually own 1.1 million Bitcoin?

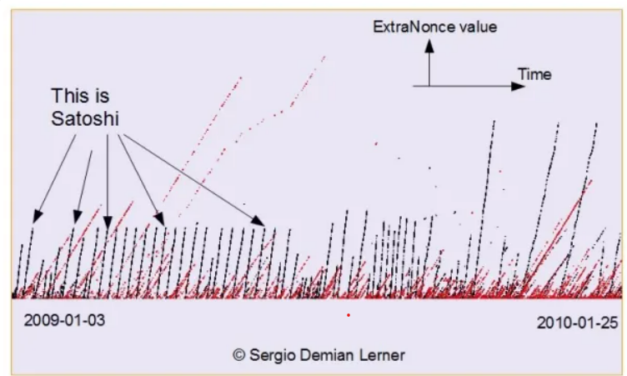
One of the first things anyone learns about Bitcoin is that it has a pseudonymous creator — and they’re a billionaire multiple times over.Nearly 1.1 million BTC is widely attributed to Satoshi Nakamoto, but it’s a number that rests on a forensic trail identifying a mining operation, not a person. The estimate also varies by more than 200,000 Bitcoin depending on how strictly a certain “fingerprint” test is applied.When 600 BTC mined in 2010 suddenly moved after 16 years, triggering speculation that “Satoshi’s coins” had awoken, that distinction became more important.The coins came from 12 long-dormant block rewards that had been mined over four days in March 2010 and sat untouched until Sept. 5 this year, when someone controlling the private keys spent them one by one within half an hour. But that doesn’t mean that the person spending that $46 million in Bitcoin was Satoshi. The blockchain traces coins, not people Onchain tracker Whale Alert found no connection between the 600 BTC and the mysterious Bitcoin creator’s stash. Blockchain research firm Bitquery found that 10 of the 12 blocks didn’t match the distinctive mining pattern that’s come to be associated with Satoshi’s mining operation, known as “Patoshi.” And the two remaining blocks only showed weak matches that could occur by chance according to Bitquery researcher Gaurav Agrawal. Related: Bitcoin treasury firms can outperform BTC… but is the risk worth taking?The rewards were mined by a single machine however, and whoever spent them this month controlled the private keys, but as Agrawal points out: “What the chain cannot say is whether the hand in 2026 belongs to the person who ran the machine in 2010.” It’s a mystery that’s likely to remain unsolved since private keys can be inherited, sold, stolen, or recovered from an old drive found in a secondhand store. Agrawal notes that “the chain only records that someone had it.” The spending transactions used modern wallet software, which the 2010 client could not have produced, so “at the very least, the keys were loaded into something new.”The Patoshi pattern behind the fortuneIf the blockchain can’t tell us who owned those OG coins, how do we know the 1.1 million BTC actually belonged to Satoshi? Circumstantial evidence is the best evidence we have.In 2013, researcher Sergio Demian Lerner identified a distinctive fingerprint in Bitcoin’s earliest blocks, suggesting one miner operated a machine differently from the other miners on the network that could be traced across thousands of blocks.Lerner estimated that the miner had amassed around 1.1 million BTC, and more than a decade later, he still stands by his calculations. Sergio Dermian Lerner identified the Patoshi pattern. Source: Bitslong“It is accurate,” he tells Magazine, “with a disclaimer that the evidence is circumstantial; there is no math proof or direct witness.”He says the case for connecting Patoshi to Satoshi goes beyond the mining fingerprint, however, since several early Bitcoin users, including Hal Finney, Dustin D. Trammell, Nicholas Bohm and Mike Hearn, received transfers that exhibited the Patoshi pattern:“All those transfers were made from coinbases in the Patoshi pattern: that provides compelling reasons that Patoshi and Satoshi are the same person, although not proof.” Lerner also says the miner appears to have been using specialized mining software rather than the standard client, which was likely created before Bitcoin launched. That makes it “highly improbable” that another miner developed a working specialized setup in the few hours between the Bitcoin v0.1 announcement and the mining of the first block. He says:“Whoever was mining the Patoshi pattern started right at the earliest beginning.” Bitquery rebuilt the fortune from scratch 13 years after Lerner identified Patoshi, Bitquery rebuilt the fingerprint from raw blocks, grading 54,316 blocks from Bitcoin’s early era and following every coin through Sept. 1, 2026. Their “highest grade” reconstruction agrees with the public Patoshi list on 99.2% of blocks, and the firm also found zero exceptions in a timestamp-ordering test across 5,836 adjacent block pairs.“I don’t know of a stronger test for this,” Agrawal says.Bitquery’s estimate of the total fortune. Source: Bitquery.ioBut the analysis casts some doubt around the famous 1.1 million BTC figure itself, since the number Bitquery found varies depending on how strictly the pattern is applied.Related: Is Bitcoin too volatile to risk your retirement on?“Run strictly, the fingerprint covers just under 0.9 million BTC,” Agrawal says, with the “most generous reading” at around 1.17 million.That isn’t to say Bitquery disproves Lerner’s estimate, but it shows how the size of the Patoshi stash depends on how the mining pattern is applied.“The published estimates of 1.0 to 1.13 million sit inside that range, so we did not move the number,” Agrawal says.What links Satoshi to the 1.1M BTCAgrawal says the claim that “Satoshi owns 1.1 million BTC” is really three claims stacked on top of each other. “Satoshi Nakamoto” is the largest BTC holder. Source: ArkhamThe claim that the coins came from one machine is supported by strong evidence. The claim that the machine belonged to Satoshi is circumstantial, and the claim that the keys still remain under his control can’t be proved simply because the coins have never moved.Bitquery also discovered a 2010 transaction that it could not find reported “in any published study.”On May 17, 2010, 600 BTC from early mining rewards moved in two transactions about an hour apart. The first, at 22:04 UTC, spent 10 block rewards worth 500 BTC, and the second, at 23:07 UTC, spent another two block rewards worth 100 BTC. Those coins had been mined at different points throughout 2009, including rewards from near the beginning, and end, of Bitcoin’s first year.“It matters, I think,” Agrawal says, “because it is the clearest moment where the chain itself, and not a statistical pattern, says these blocks belong together.” He says that is “as close as the chain gets” to confirming that blocks from all over 2009 sat in one wallet, “which is what the pattern claims for the whole set.”So we know whoever controlled those keys had access to block rewards mined across 2009, but we don’t know who was behind them. Unlike the May 2010 transaction, the 600 BTC that moved this September don’t belong to the Patoshi miner, and there’s no new evidence connecting them to “Satoshi’s” stash. As Agrawal says, “nothing in the math settles it, so we will never be sure.”Related: 10 of the greatest unsolved crypto mysteriesCointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Čítaj viac
Is there any chance left to save the CLARITY Act?

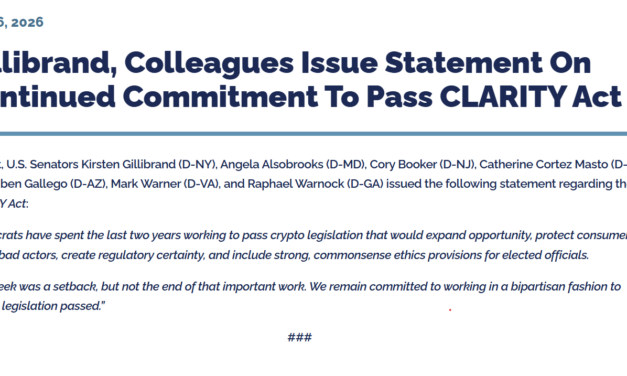
Water, water everywhere and not a drop to drink may be the sentiment of the crypto industry, lobbyists and lawmakers who’ve spent the last year trying to get the CLARITY Act over the line. No shortage of negotiations, amendments or political wrangling; yet not enough to get the bill moving through the Senate. The CLARITY Act may have rammed into a Senate-shaped hurdle this week, but it isn’t dead on arrival yet — let’s go with walking wounded.There’s still a chance for the digital asset market structure bill to scramble together the 60 votes it needs to clear the Senate.When Republican Senator Thom Tillis switched his vote from yes to no at the last minute, he did so on procedural grounds. It may have looked like a swing against CLARITY, but it was really a parliamentary maneuver, allowing him to file a motion to reconsider and preserve a route back to the Senate floor.The Crypto Council for Innovation (CCI)’s director of US federal affairs, Ryan Eagan, tells Magazine:“Senator Tillis’s motion to reconsider would provide an opportunity to revisit CLARITY’s cloture vote at any point this session. Specific timing regarding next steps is not clear, but that desire to preserve that opportunity is in part due to the progress made over the past week.”But the Senate is running out of time; both Democrats and Republicans remain divided over ethics provisions involving President Donald Trump, and even supporters of the bill say a more bipartisan negotiating process may now be necessary.So can CLARITY still be resuscitated, and if it can, how much of the bill will need serious CPR to get there? CLARITY isn’t dead, but the clock is running downThe failed cloture vote, a procedural vote to end debate on a bill and move it toward a final vote, doesn’t end CLARITY’s journey through Congress just yet. It requires 60 votes in the Senate, and CLARITY fell 49-50 on Tuesday.Tillis’ motion to reconsider means the vote can be revisited during the current session, but that route is running into a much more practical problem: a ticking clock.Related: Coinbase faces greater fallout from CLARITY Act setback: SaxoThe Senate is scheduled to leave for recess on October 2 before returning after the midterm elections, and the House of Representatives has already recessed for the election period, complicating any attempt to move legislation through both chambers before the end of the year.Congressman Shri Thanedar, a Democrat who supported CLARITY when it passed through the House in July 2025, tells Magazine that timeline presents a “major barrier” to reaching an agreement:“There are only 20 legislative days left in this Congress, all of them after the midterms, making odds of a 2026 compromise, unfortunately, very low.”Very low doesn’t mean impossible, and the crypto industry has a precedent in the Guiding and Establishing National Innovation in US Stablecoins (GENIUS) bill, which failed cloture 48-49 in May 2025 before clearing a second cloture vote 66-32 just 11 days later. It passed the Senate the following month. However, Kyle Chassé, founder of crypto investment firm MV Global, tells Magazine:“GENIUS came back from a failed cloture in 11 days. But GENIUS had a deal. This one has a calendar and no votes. Miss Jan. 3, and it restarts from zero in 2027 with a House that is probably Democratic.”While a lame-duck session after the November elections could give CLARITY another shot, that’s not the same as having a ready-made deal waiting to go. The 60-vote problem is a negotiating problemOf the 49 votes for CLARITY, not a single one came from the Democratic camp. Chassé says:“Every one of the 49 was a Republican. Zero Democrats voted to even open debate.”While that’s clearly less than ideal, it doesn’t necessarily mean the Democrats have abandoned the bill entirely.On Wednesday, seven Democratic senators — all of whom had voted a day earlier against advancing the bill — said they “remain committed” to enacting the legislation. Among them was Sen. Angela Alsobrooks, who backed moving the bill out of the Banking Committee in May before voting no on cloture. She said it’s “clear that now is the time to regulate digital assets” and that she’s willing to negotiate over the ethics provisions, adding:“We were ready to strike a deal today and in discussions right up until the vote. Republican leadership shut it down at the very last minute after it became clear that we were on a path to a successful vote.”Tillis said Wednesday he now wants to “convince the Democrats to get on board,” and “put pressure on them to own it,” and his procedural vote switch was designed to keep that possibility alive. “I feel very strongly that this is an unregulated marketplace and that we need some guardrails on,” he added.Related: Bernstein expects ‘aggressive’ rulemaking from SEC, CFTC, following CLARITY Act failureThe divide isn’t over whether Congress should establish rules for crypto anymore, but whether the current package goes far enough to secure bipartisan support. Seven Democratic senators “remain committed” to enacting the legislation. Source: Kirsten Gillibrand, SenateWhile Congressman Thanedar says he supports the bill in its current form, he acknowledges that Tuesday’s result shows the need for both parties to work together further on the draft:“I do believe that the failed CLARITY vote on Tuesday demonstrates that a more bipartisan drafting process would lead to a higher likelihood of creating the bipartisan, supermajority coalition that passing this legislation into law would require.”If saving CLARITY means rewriting it, what survives?Chassé says the problem has moved beyond the technical drafting of crypto policy and is now centered on President Trump’s crypto interests and the ethics provisions around them:“This stopped being a drafting problem. It’s a referendum on the President’s crypto holdings six weeks before an election, and the text as written can’t survive that.” Republicans had already made 126 substantive changes requested by Democrats ahead of Tuesday’s vote, including tighter restrictions on public officials profiting from crypto ventures, and giving state attorneys general a role in enforcing some of the ethics provisions. Alsobrooks votes no on CLARITY. Source: Angela Alsobrooks, Senate.Despite the concessions, Thanedar says the Democrats want more restrictions “on the President’s ability to use his office for personal gain.” He says the at least $1.4 billion in crypto earnings Trump reported for 2025 in his annual financial disclosure shows that “guardrails are necessary to both hold the President accountable and protect the long-term health of the digital asset market.”Ethics is not the only potential fault line, though, and Chassé says the industry “should stop dying on that hill.” He points instead to stablecoin rewards, saying “some kind of cap or circuit breaker on yield” would likely be “the price of the bank-side senators and a chunk of Democrats,” along with “tighter illicit finance and state enforcement language.”He says self-custody and developer protections are areas the crypto industry should be reluctant to trade away. Those protections have been bitterly defended throughout the negotiations, with lawmakers and industry groups debating how far the bill should go in shielding non-custodial developers from financial and anti-money-laundering (AML) requirements. Congress may stall, crypto regulation doesn’t have toEven if CLARITY remains stuck in Congress, US crypto regulation is not standing still. Eagan says the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) have “demonstrated commitment to reduce uncertainty” through guidance, rulemaking, no-action relief and exemptions.“CCI expects that agencies’ crypto agenda will proceed in robust fashion regardless of the CLARITY Act,” he says, adding that the GENIUS Act implementation continues at Treasury and the banking regulators.Strategy executive chairman Michael Saylor also pointed out that the SEC, CFTC and Treasury could continue to advance rules under existing laws:“Progress need not wait for Congress.”That may be true, but agency action is not the same as getting CLARITY over the finish line. Regulatory guidance can be swept out with administrations, but legislation is harder to unwind.CLARITY may still have a way to limp back to the Senate, but whether lawmakers can find 60 votes without changing the bill beyond recognition is another matter.Magazine: Revolut ID thefts highlight KYC’s dangers: Here’s how to fix itCointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Čítaj viac
Bitcoin treasury firms can outperform BTC… but is the risk worth taking?

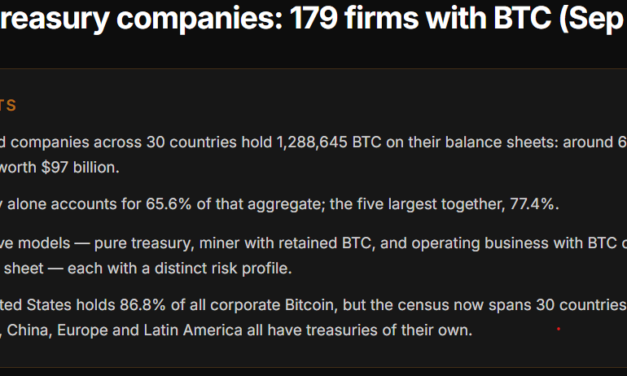
There are now 179 listed companies holding Bitcoin on their balance sheets, all following variations of the same simple formula:Raise capital on traditional markets, buy Bitcoin and attempt to increase the amount of BTC that backs each share faster than the company dilutes shareholders. According to Mark Palmer, managing director and senior equity research analyst at StoneX, that’s how treasury companies attempt to “beat” Bitcoin’s returns.Making that equation work is a lot easier when the price of Bitcoin is going up and investors are happy to fund the next spree of purchases. Unfortunately, the mechanics work in both directions. When the premium evaporates, investor enthusiasm wanes. Financing gets harder, debt and yield obligations remain, and the same structure that outperformed the asset magnifies the losses on the way down. No surprise that the 50 largest Bitcoin treasury companies bled $83 billion in market value since July 2025.Metaplanet’s recent shareholder backlash shows the sort of questions that arise when treasury companies dilute their shareholders too much. Treasury companies are more likely to need to raise money in bear markets, but this creates a potential problem. Palmer says:“Issuing shares at a premium to net asset value and buying Bitcoin with the proceeds increases the Bitcoin backing every existing share. The same issuance at a discount destroys value.”So are the outsize returns on offer during the bull market, worth it for the downside risks during the bear?The math works, until the capital markets stop cooperatingFor all the complexity around Bitcoin treasury companies, the basic test for potential investors is relatively simple. Do shareholders end up with more Bitcoin backing each share over time?Palmer says investors should look past the headline number of Bitcoin a company holds and focus instead on “Bitcoin per fully diluted share, net of debt and preferred stock claims.”179 Bitcoin treasury companies as of September 2026. Source: SatsIntelIssuing new shares is not necessarily a problem. What matters, is whether the new capital generates enough additional value and profit that the benefits to existing shareholders outweigh the dilution.Related: Metaplanet moves 4,800 BTC worth $377M to Coinbase PrimeIf the company issues shares for more than the value of the Bitcoin that backs them, and uses that money to buy more Bitcoin, shareholders can end up with more Bitcoin per share. If it raises money below that value, they can end up with less. That dynamic was very favorable for Strategy during the last Bitcoin bull market, McCarthy says, because Bitcoin was increasing fast. “They were able to take on new debt. They were able to issue new debt because of that.” The first blow is half the battleChoosing the right digital asset treasury is a key decision. With a couple of hundred now on offer, longer established companies have the advantage, explains McCarthy:“It’s a first-mover advantage, right? Like if you’re Michael Saylor or you’re Bitmine and you’ve got this sort of larger-than-life character at the top, it’s a bit different.”Strategy’s executive chairman Michael Saylor has become part of the machinery of the trade itself, and McCarthy says he can keep the story moving even when Bitcoin’s price isn’t. Ethereum treasury company Bitmine has a similarly prominent figure in Tom Lee.Bitcoin and other cryptocurrencies rise and fall on narratives, so having a storyteller out front helps keep investors interested — especially when the underlying asset is in freefall. But McCarthy warns: “I don’t think there’s enough room for a hundred Michael Saylors; there’s not enough people like that around.” Related: Strategy raises $334M through stock sales but buys no BitcoinMcCarthy says many of the companies that followed Strategy were essentially just buying Bitcoin and hoping the stock price would follow. They “didn’t have an exit plan” for when the dynamics reversed, he says, and he expects the shakeout to be even more brutal still: “I think it’s going to flush out like 95% of it.” The corporate wrapper comes with baggageThere are also simpler ways to get exposure to Bitcoin by just buying it directly on an exchange, or via a spot Bitcoin exchange-traded fund (ETF).Spot ETFs let TradFi investors buy Bitcoin through a conventional brokerage account, without having to consider a DAT’s company’s management, financing structure, or governance risks.Creative financial engineering can be difficult for retail investors to understand, says Palmer:“The biggest risk that investors face in buying Bitcoin treasury company stocks is forgetting that common shareholders’ claim is a residual one, as convertible debt and perpetual preferred stock sit ahead of them in terms of priority.”Those instruments, he adds, “carry cash obligations that Bitcoin itself doesn’t generate.”So, can treasury companies beat Bitcoin?Matt Cole, chief executive of Strive, one of the largest Bitcoin treasury companies, says investors should just look at the scoreboard:“Strategy has dramatically outperformed Bitcoin since adopting its strategy. Metaplanet has also outperformed Bitcoin since inception and Strive has outperformed Bitcoin both since announcing our strategy in May 2025 and year-to-date in 2026.” He adds that, “Strive has not sold a single Bitcoin, and during a Bitcoin bear market we have increased our holdings approximately fourfold while outperforming Bitcoin.”David Bailey, chief executive of Nakamoto, makes a similar case for Metaplanet, saying it was “the best performing equity in the world for nearly two years” and is “up 1,300% from genesis.”David Bailey says Metaplanet best performing equity for 2 years. Source: David Bailey.Despite the returns to date, debt maturity and yield obligations may still cause problems down the line. And some companies without the same access to capital, investor following or balance sheet firepower have found out how quickly the trade can work against them. The two most notable examples are Bailey’s own Nakamoto Inc, whose stock fell 99% from its 2025 peak and the UK company Satsuma Technology, which saw a similar decline. McCarthy’s own view is telling. When asked how he would deploy $100,000 for Bitcoin exposure, he says he would “mostly buy an ETF” and might put a smaller amount into Strategy “for the vol.”At the end of the day, buying Bitcoin is a bet on Bitcoin. Buying a treasury company is a bet on Bitcoin plus an additional bet on the people, financing structure, balance sheet and corporate governance wrapped around it.Magazine: Strategy became a symbol of the dot-com crash: Could history repeat?Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Čítaj viac
Revolut ID thefts highlight KYC’s dangers: Here’s how to fix it

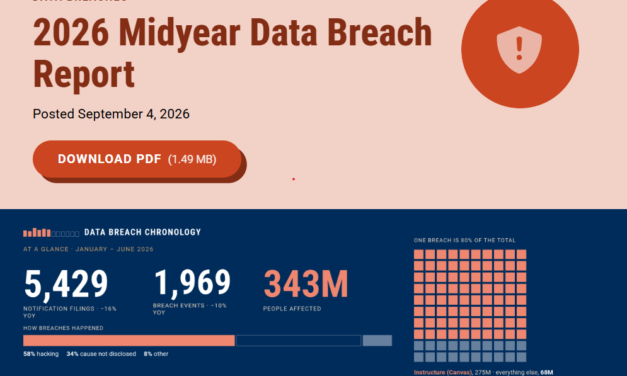
The massive theft of more than 153 million US and Canadian driver’s licenses earlier this month should make one thing abundantly clear: the safest place for a copy of your driver’s license is nowhere at all.The leaked IDs, which appear to have come from an identity verification provider, ended up on a dark web identity service dubbed Nexus, alongside millions of other stolen identity and travel documents.The danger was underscored this week after fintech Revolut revealed it had been tricked by a hacker into handing over reams of sensitive customer data, including copies of passports and verification selfies. The hacker is now drip feeding the identification documents of 680 customers onto the web in an attempt to secure a 10,000 Bitcoin ransom.The irony is hard to miss: Know Your Customer (KYC) processes are designed to make financial systems safer by establishing who customers are and making sure they’re not up to nefarious deeds. But the way KYC is usually implemented requires companies to store vast quantities of sensitive information, which creates valuable honeypots for criminals.And the problem is getting harder to ignore. In the first half of 2026 alone, US data breaches affected at least 343 million people, according to the Privacy Rights Clearinghouse. Even more frustratingly, it’s already possible to verify an individual’s identity without storing their identity documents using zero knowledge proofs:Efrat Fenigson, host of You’re The Voice podcast, writes and speaks extensively about privacy and KYC. She tells Magazine:“When regulators keep mandating a model that guarantees this outcome — while the technology to verify without storing already exists — it raises a red flag. It implies there is a lack of rational thinking and real will to solve problems.”So how many more of these leaks will it take before that will starts to bend? KYC was built to collect your identity, not just verify itKYC systems today have pretty much evolved around the assumption that institutions should see customers’ passports or driver’s licenses, record the relevant information and then store evidence of the check.343 million people have already been affected by US data breaches in 2026. Source: Privacy Rights Clearinghouse.But there’s an obvious problem with that approach: it has created a vast ecosystem of identity providers, databases, vendors and compliance systems that all store separate treasure troves of your individual KYC data. Every additional copy of your data creates another potential point of failure — and hackers are increasingly creative about devising ways to access it. In the Revolut case, the hacker sent emails requesting the KYC data from a legitimate Italian law enforcement address. Lyudmyla Kozlovska, Open Dialogue president said on X that EU laws meant Revolut had no other option but to comply.“EU AML law imposes no verification duty on the bank and provides no meaningful mechanism to check who is really behind an authenticated state request. Refusal to answer carries fines in the millions. In practice, verification is impossible.” Related: 200,000 fake AI ‘victims’ deployed to scam bait online fraudstersSusie Violet Ward, director and co-founder of Bitcoin Policy UK, warns the real issue is in storing ID data unnecessarily:“We need to stop treating identity verification and surrendering your identity as though they are the same thing.”If a company only needs to know that someone is over 18, she argues it should not automatically need additional details like your full name, address, exact date of birth, and a permanent copy of the relevant identity documents:“The irony is that KYC is designed to make systems safer, but the way we currently implement it can create an entirely different security problem. You can reset a password after a breach, but you cannot reset your identity in the same way.”The technology to stop hoarding IDs already exists For crypto proponents, the obvious solution is to use zero knowledge proofs. That’s a mathematical proof that demonstrates something is true without revealing the details. For example, you can use an phone app to generate a proof confirming your drivers license says you are older than 18, without sending through your birth date, or a picture of the license itself.Zcash founder Zooko Wilcox provides a useful explanation of ZK tech in this video. A useful explanation of ZK tech. Source: Crypto FiresideEvin McMullen, chief executive and co-founder of Billions Network, which develops privacy-preserving digital identity and ZK solutions, tells Magazine:“The technology works and is in production today, across thousands of applications and regulated institutions. What holds it back is that the entire compliance stack was built around collecting and storing copies of documents.”McMullen says the barrier was “never the technology,” but the rules, incentives and infrastructure built around it:“This is a governance and standards problem wearing a technology costume.” If the technology works, what’s stopping it?The European Union is already incorporating ZK technology into its digital identity and age verification systems design, developing privacy-preserving age verification that allows users to prove their age without revealing their full identity or exact date of birth. Related: Fears of AI-driven DeFi hack epidemic overstated for now — but not for longIts Digital Identity Wallet also supports “selective disclosure,” so users reveal only the information needed for a particular transaction. So, why isn’t this being deployed more widely for financial KYC?According to McMullen, “regulation and understanding” are the biggest obstacles to adoption:“The most common blocker is that compliance teams conflate ‘we saw the ID’ with ‘we must keep the ID,’ so they over-collect to be safe.” She says interoperability is another issue, since cryptographic proofs are only useful “if the party relying on it can check it without calling back to whoever issued it.” That requires putting shared standards in place, which is easier said than done. ZK doesn’t magically solve KYC There is another important caveat: replacing an ID document with a zero-knowledge proof doesn’t automatically eliminate every privacy or security problem.Fenigson points out that what a ZK credential remains tied to is equally important: “The incentives point toward control, not privacy. Zero-knowledge proofs let someone prove a fact, like being over 18 or not on a sanctions list […] What’s missing is what that proof gets bound to. Right now it’s usually bound to an account inside someone else’s database.” The EU’s Digital Identity Wallet supports selective disclosure. Source: European CommissionSo it boils down to who ultimately controls the credential. If a person generates a privacy-preserving proof but that proof is tied to an account in somebody else’s database, they’re still dependent on a centralized intermediary.The rules aren’t as clear-cut as you might think In many cases the rules don’t actually require storage of ID data — it’s more of a convention, because that’s the way it’s always been done.The Financial Action Task Force (FATF)’s guidance explicitly considers how digital ID systems can be used to conduct customer due diligence, rather than requiring institutions to rely on physical identity documents. FATF’s recommendations also operate as a risk-based framework, leaving individual countries to implement standards through their own legal and regulatory systems.“In many regimes, the rule is that you must verify identity and retain records of that verification, not that you must keep the raw document image forever,” McMullen says.That means a cryptographically verifiable attestation with a record showing the relevant check was performed could be enough to comply without creating another permanent copy of the ID.But because the guidance is “ambiguous,” McMullen says institutions just default to keeping everything because their compliance teams know auditors and examiners will accept it.In other words, even if the rules technically permit a different approach, nobody is willing to be the first to risk it, as Ward explains:“There is an instinct in regulation that more information means more control and therefore more safety.”It’s hard to see that changing unless the rules are amended to explicitly allow zero-knowledge proofs. And while no system is perfect, at least ZK tech prevents the need to collect and retain so much sensitive information. As McMullen says:“You cannot lose what you never held.”Magazine: 10 of the greatest unsolved crypto mysteriesCointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Čítaj viac
Získaj BONUS 8 € v Bitcoinoch

nakup bitcoin z karty

Registrácia Binance

Burza Binance

Aktuálne kurzy